Tax Audit Due Date Extended to 21 October 2026
CBDT has moved the AY 2026-27 tax audit report date to 21 October 2026 and the audit-case ITR due date to 21 November 2026.

Income tax filing, planning and notices — ITR forms, deductions, regimes and refunds explained.
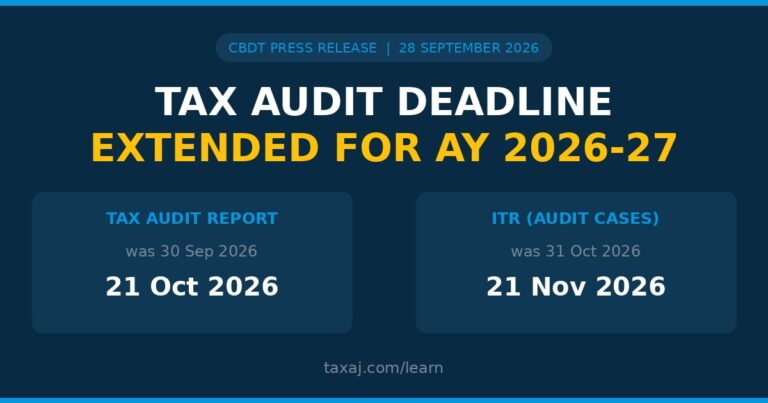
CBDT has moved the AY 2026-27 tax audit report date to 21 October 2026 and the audit-case ITR due date to 21 November 2026.
Form 10F is carried forward as Form 41 under the Income-tax Act 2025. What a foreign vendor must give you before you pay – TRC, Form 41 and PAN – and how it fits 15CA/15CB.
Bank deposits, insurance, mutual funds, shares, dividends and NPS — how the Ministry of Finance unclaimed assets portal works, the claim process for each asset type, time limits, and why any agency asking for an advance recovery fee is a fraud.
The higher TDS and TCS rates for non-filers were omitted from 1 April 2025, and TCS on sale of goods went with them. What to switch off in your payment process, what still triggers a higher rate, and where TDS on purchase of goods now stands.
Business and professional taxpayers must file Form 10-IEA before the return due date to use the old regime. Who files it, who does not, why it cannot be withdrawn in the same year, and why a late return costs you the regime entirely.
Complete slab tables for both regimes, the Section 202 rebate that makes twelve lakh tax-free, standard deduction, surcharge and cess, and a straight answer on which regime tends to win and why.
Registering and logging in at incometax.gov.in, downloading the AIS and Form 26AS before you file, filing and verifying the return, paying tax under the right head, uploading an audit report, registering a DSC, and tracking a refund.
An unlinked PAN goes inoperative: refunds are withheld, no interest accrues on them, and TDS is deducted at a higher rate. Who is exempt, how to link and pay the fee under the right head, why linking fails, and how long reactivation takes.
Learn about the status of wealth tax returns after abolition from AY 2016-17, legacy wealth tax notices, Form BB filing, old demands, pending appeals, and asset disclosure requirements.
Income Tax Refund Re-Issue Process — When Refund Fails to Credit Introduction An Income Tax refund is generally issued after the Income Tax Return (ITR) has been processed and the taxpayer is determined to have paid more tax than the final tax liability. However, even after a refund has been determined and issued, the amount…